Do you know who pays for a burst pipe? You do, unless you have a policy. So buyers ask what homeowners insurance is. It’s a yearly plan. It covers damage to your home and your belongings. It also helps if a guest sues you.
Lenders ask for it before they fund your loan. Most buyers learn the details too late. We’ve seen closings slip over one missing paper. You’ll get plain answers on cost, coverage, and closing papers. You’ll also see how Sai Mortgage helps Virginia buyers.
Table of Contents
ToggleWhat a Homeowners Policy Covers
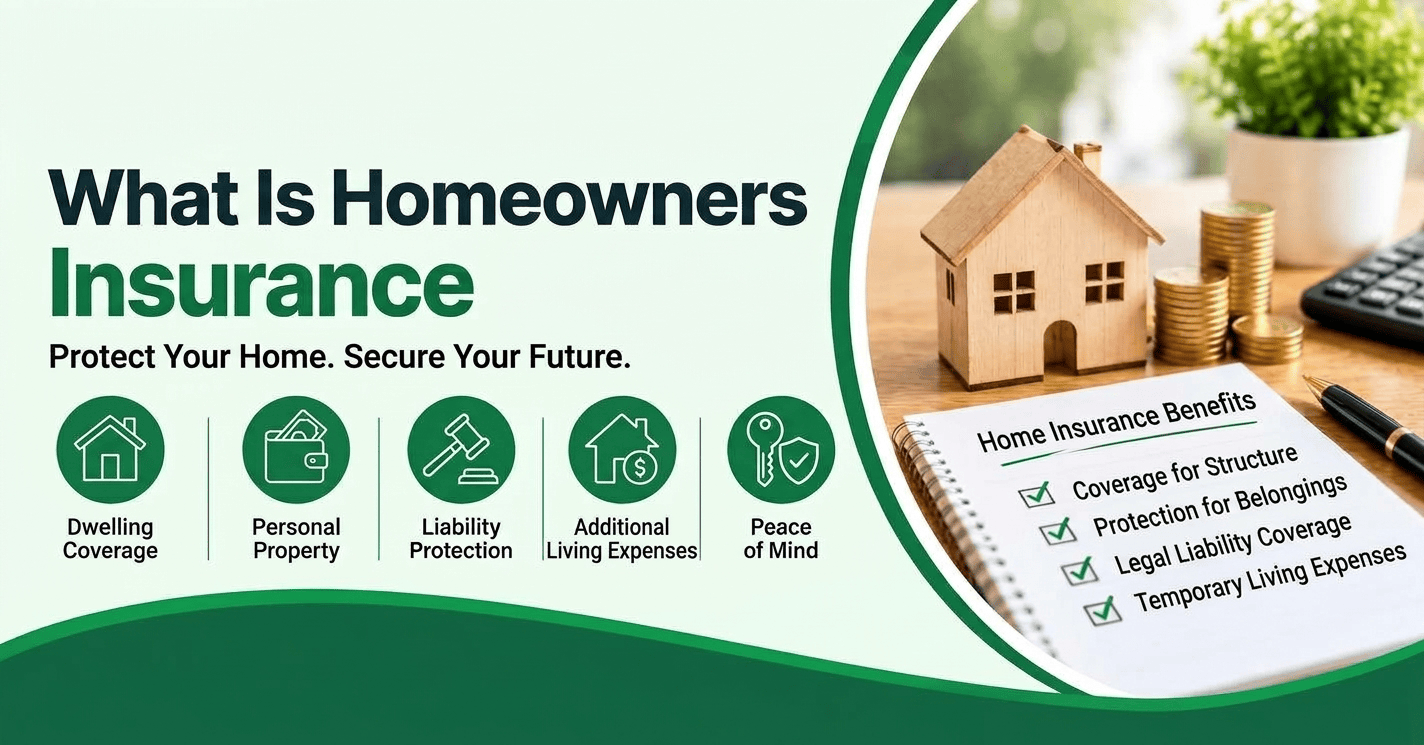
So what is homeowners insurance made of? Four main parts. Each part protects something different. Read them before you pick a plan. Your agent should explain each one with examples. Ask for the answers in writing. A clear quote beats a verbal promise. Your lender will check all four.
- Dwelling Cover: It pays to repair damage from fire, wind, or hail. This covers your roof, walls, and floors. Lenders care about this part most. A new roof often lowers the premium.
- Personal Property: Thieves took your laptop? This part pays you back. It also covers couches, clothes,s and TVs after a fire. Take photos of your things now.
- Liability Cover: A guest slips on your steps and sues. This part pays legal bills and medical costs. It protects your savings. Many plans start at $100,000 in liability cover.
- Extra Living Costs: A fire forces you out of your house. This part pays for a hotel and meals. Ask about the time limit. Some plans stop after 12 months.
- Hazard Insurance: Lenders say hazard insurance for home loans. It’s the damage part of your policy. Hazard is one slice, not the whole plan. Papers sometimes say hazard coverage. Ask your lender what it means.
Read your policy once a year. Rates and coverage change, so a quick review saves money. Add a deck or pool? Call your agent. A new roof counts too.
How Much Homeowners Insurance Costs
After what homeowners insurance is, price is the next question. Cost shifts with roof age, storm risk, and coverage limits. Two nearby houses often get different quotes. Get three quotes before you pick. Compare them line by line, not by price alone.
What You Pay Each Year
Many US buyers pay roughly $2,000 to $2,500 a year. Wonder how much homeowners insurance is on a $400,000 house? Ask for local quotes. Older roofs and storm zones push the price up. Averages only give a rough guide, so get real quotes. Credit, claims history, and old wiring also move your price. Ask about flood cover too. A normal policy skips floods. Flood plans come from a separate insurer. Bundle your car policy to save more.
Your Deductible
A normal home insurance deductible runs $1,000 to $2,500. Storm plans use 1% to 2% of home value. A higher deductible lowers your yearly bill. Pick an amount you have in savings. Don’t guess here. A $2,500 deductible hurts when your account is empty. Many buyers pick $1,000 and pay more monthly.
Is It Tax Deductible?
Is homeowners insurance tax deductible? Not for your main home. Rental owners and home offices follow different rules. Ask a tax pro about your case. Don’t claim it on a hunch. A wrong claim costs more than the premium. Your lender won’t give tax advice either.
Closing Day Papers to Know
Closing day brings a stack of papers. Several deal with insurance. Know each one before you sit down. Your lender won’t fund the loan without them. Ask your loan officer for a checklist a week early. Missing one paper delays keys more often than you think.
- Insurance Binder: An insurance binder is short proof of coverage. It lasts 30 to 90 days. Your lender asks for it before closing.
- Mortgagee Clause: The homeowners insurance mortgagee clause names your lender. Big claim checks often list you and the lender. Both must sign. Ask your agent to add the lender’s name early. A refund check arrives if you pay off the loan.
- Escrow Payments: Is homeowner insurance included in mortgage payments? Often yes. Your lender holds the cash in escrow. Then it pays the bill. You skip the big yearly bill. Check your escrow statement once a year, since rates rise.
- Lender’s Title Insurance: Lender’s title insurance protects the bank from old land claims. You pay once at closing. Title insurance cost often runs 0.5% to 1%.
- Owner’s Title Insurance: An owner’s title insurance policy protects you instead. It’s a one-time fee too. Buying with cash? Get it anyway. A hidden lien costs far more.
Print these five items and bring them to closing. Your closer will tick them off one by one. You’ll feel calm instead of rushed.
When Your Home Doesn’t Fit a Standard Plan
Some homes don’t fit a normal policy. Empty houses and building sites need special cover. Standard answers to what is homeowners insurance miss these cases. Tell your agent your plans early. Tell your lender too. A wrong policy gives you a denied claim.
Vacant or Unoccupied Homes
Most plans cut coverage after 30 to 60 days empty. Vandalism and frozen pipes often drop out. Ask about vacant home insurance if you plan a gap. It costs more, but it pays when trouble hits. Check the house weekly. Keep the heat on. Read your policy for the exact day count.
Homes Under Construction
A builder’s risk policy covers a home during the build. A normal homeowners plan starts after you move in. Don’t mix them up. Ask your builder who carries the cover. Get proof in writing before work starts. Then call your agent before move-in. Cover should start with your keys.
Home Warranty vs Homeowners Insurance
A home warranty fixes worn-out items like ovens and furnaces. Homeowners insurance pays for sudden damage like fire. They’re not the same. A warranty won’t replace a burned roof. We’d buy insurance first and treat a warranty as optional. Read the warranty’s exclusion list before you pay. Many claims get denied for old wear.
Don’t Mix Up MPI With Your Policy
Mortgage protection insurance, or MPI, solves a different need. Don’t mix it with what is homeowners insurance. It pays your loan if you die or get hurt. Some plans cover job loss. Your home policy never does this.
Costs vary by age and loan size. Quotes differ a lot between sellers. Compare plans first. Read every exclusion line. Term life insurance often gives more coverage for less money. Ask about mortgage disability insurance too.
Sai Mortgage Helps You Close With the Right Papers
We explain what homeowners insurance is. We also list what your lender needs. Sai Mortgage is an independent mortgage broker in Vienna, Virginia. We hold NMLS ID 179997. We serve Virginia, Washington, D.C., and Maryland. We shop many lenders for one file. So a bank’s no is not the end. Our loans include conventional, FHA, VA, and USDA.
We also do jumbo, bank statement,nt and DSCR loans. Most pre-approvals take one to two days. Most loans close in 30 to 45 days. Our team speaks eight languages, including Urdu, Punjabi, Arabic, and Spanish. You talk to the person handling your loan. Clients tell us we explain every step. We also help you plan closing cash. This includes your first insurance payment. Call (703) 980-1663 for a straight answer.
Conclusion
You now know what homeowners insurance is. You know the cost and the proof. It protects your biggest purchase. Get three quotes. Pick a deductible you have saved. Ask for your binder a week before closing. Skip the rush. A late binder delays your keys. Call your lender early so nothing stalls. Questions about your loan? Call Sai Mortgage at (703) 980-1663. We’ll answer in plain words.
FAQs
What is homeowners insurance?
Homeowners insurance is a yearly plan. It pays for damage to your home and belongings. It also pays legal bills if a guest sues you. Lenders require it before closing. Shop quotes early.
Is hazard insurance the same as homeowners insurance?
Not quite. Hazard insurance pays for damage only. Hazard is one slice of what homeowners insurance is. Your full policy adds liability and personal property coverage.
Do you need homeowners insurance with a mortgage?
Yes. Every lender requires it. Without a policy, the lender buys one for you. The lender’s plan costs more and covers less. Avoid the trap.
How much does title insurance cost?
Lender’s title insurance often costs 0.5% to 1%. Owner’s coverage costs similar amounts. It’s a one-time fee at closing. Ask for a quote early.
Is homeowners insurance tax deductible?
No, not for a main home. Rental owners and home offices follow other rules. Ask a tax pro before you claim it.